Valterra Platinum pays R15.1bn interim dividend as EBITDA quadruples to R33.4bn
An 85% jump in the dollar basket price and Amandelbult's recovery from the 2025 floods drove the third-highest interim profit in the company's history
Valterra Platinum, the former Anglo American Platinum, reported a four-fold increase in EBITDA to R33.4bn for the six months to 30 June 2026 and declared an interim dividend of R15.1bn, equal to 70% of headline earnings and well above its 40% policy.
Headline earnings per share rose to R82.02 from R4.73 a year earlier, with headline earnings of R21.5bn. The dividend of R57.00 a share comprises a base payment of R32.50 in line with policy and an additional R24.50. Miningmx noted that the payout follows the special dividend Valterra declared with its full-year results in February.
Prices did the heavy lifting
The realised basket price averaged $2,801 per PGM ounce, 85% higher year on year, or R45,993 in rand terms, up 66%. Volumes helped too. Metal-in-concentrate production rose 4% to 1.52Moz, refined output climbed 25% to 1.74Moz and sales increased 18% to 1.74Moz. Part of the refined boost came from moving planned processing maintenance into the second half, partly to avoid higher winter electricity tariffs.
Own-mined output improved 6%, helped by Amandelbult, where production rose 9% as the Limpopo mine recovered from the flooding of February 2025. Chrome yields at Amandelbult also improved. At Mogalakwena, Jameson flotation cells raised mass pull by 15%, cutting the volume of concentrate sent to the smelters.
Cash unit costs were flat at R20,677 per PGM ounce and all-in sustaining costs fell 21% to $996 per 3E ounce. Free cash flow was R25.5bn and Valterra moved to net cash of R23.7bn, from net debt of R4.9bn a year earlier. Three people died at its operations in the half, against one in the first half of 2025.
Cost pressure from the Middle East
Chief financial officer Sayurie Naidoo told Miningmx that hostilities involving the US and Iran had added about R250m of inflation in the first half and that guidance assumes an oil price near $90 a barrel for the rest of the year. Valterra kept 2026 guidance intact: production of 3.0Moz–3.4Moz, unit costs of R19,000–R20,000 an ounce, AISC of $1,050 per 3E ounce and capital expenditure of R17bn–R18bn. It expects a further R1.5bn in savings by 2027 as transitional services from Anglo American are wound down.
Chief executive Craig Miller said the re-rating of the basket had been broad-based, with iridium, ruthenium and rhodium all contributing. According to Miningmx, he said: “Every single PGM price was materially higher than where we were in 2021.”
What comes next
Naidoo cautioned that the company would exit the year with a weaker basket than in the first half, as platinum and palladium prices had fallen about 20% this year, and that heavier capital spending would trim second-half cash flow. Projects to watch include the repurposing of the Mortimer smelter, targeted for completion in 2027, and the Sandsloot underground feasibility study at Mogalakwena, with a decision expected in the first half of 2027. Miller also said plans to expand chrome output at Mogalakwena and Mototolo would be detailed at year-end.
Sources
- Investegate (RNS): Valterra Platinum: Interim results and board committee change, 29 Jul 2026
- Miningmx: Valterra Platinum to pay R15.1bn bumper interim dividend, 29 Jul 2026
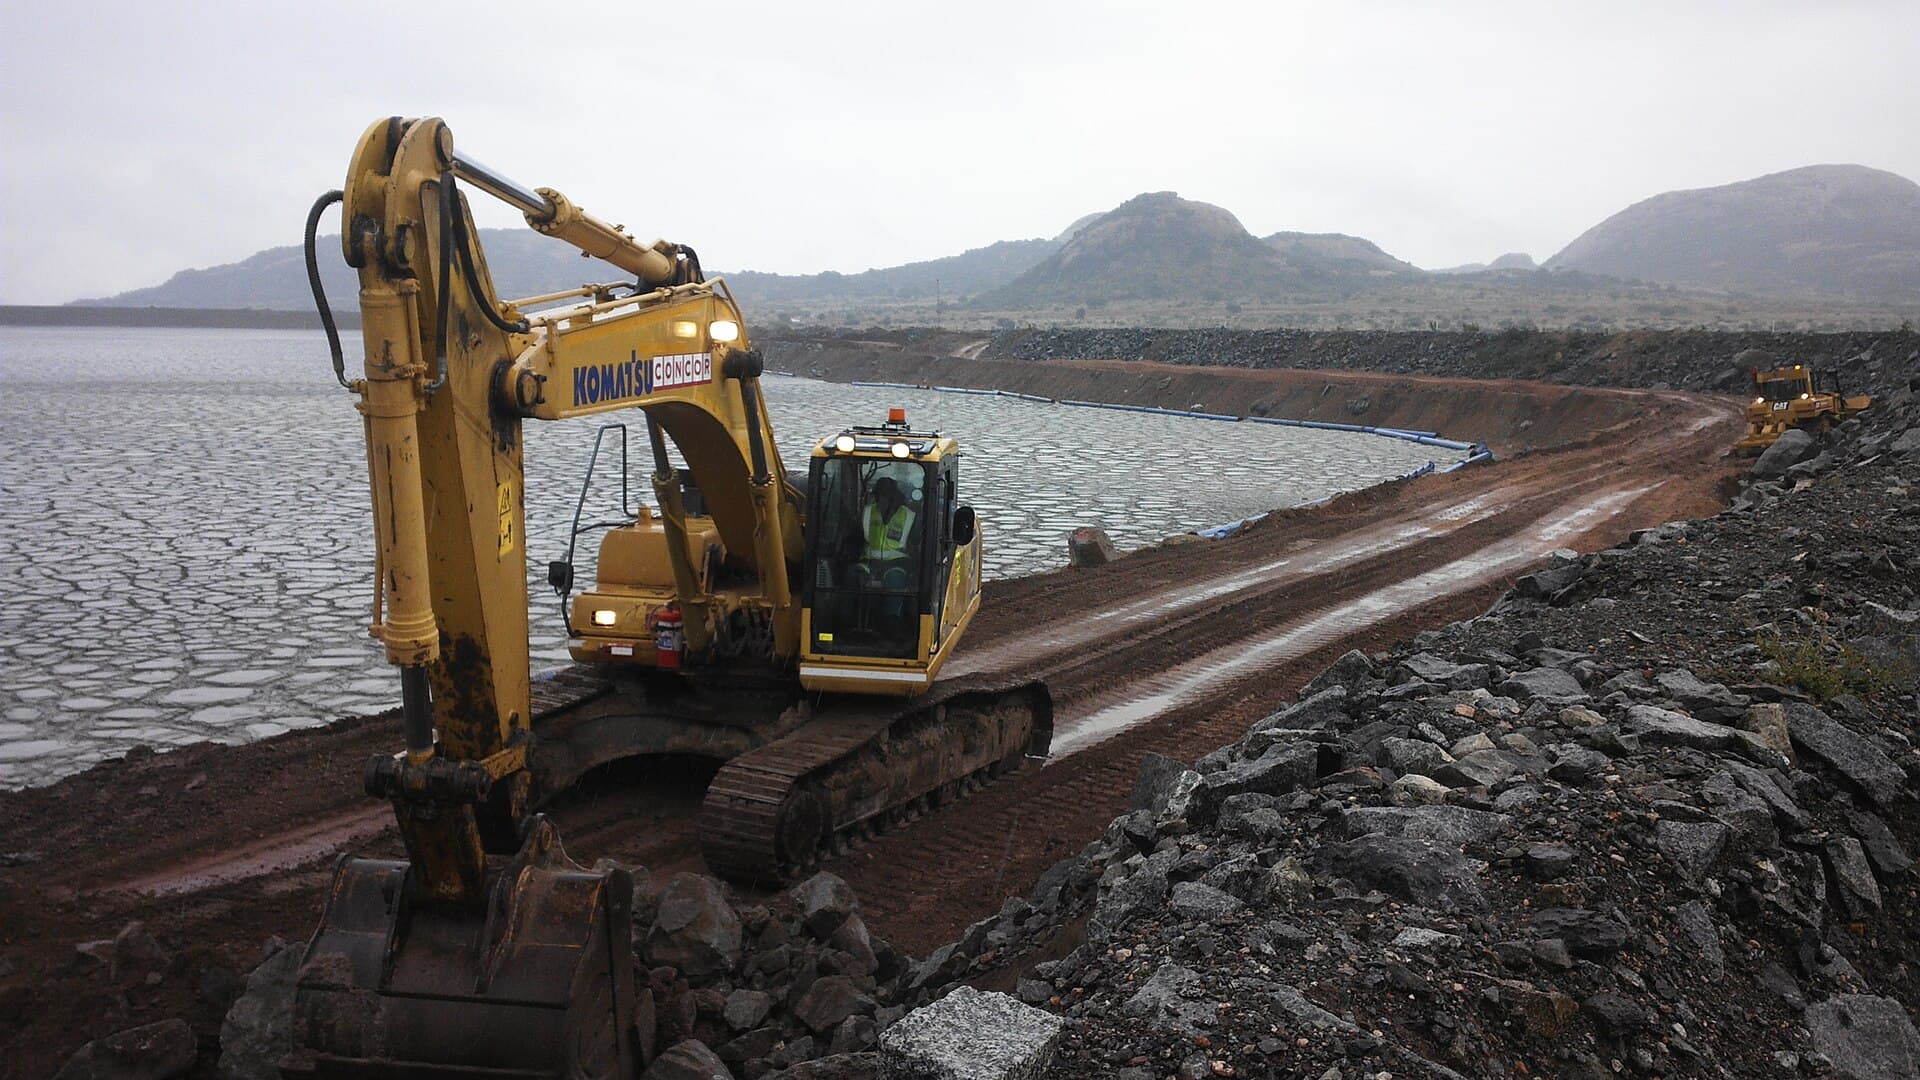
Photo: Construction of a tailings wall at the Potgietersrus Platinum operations, now Valterra's Mogalakwena mine in Limpopo. Bruce Paulmac, Wikimedia Commons, CC BY-SA 3.0.
Was this useful?
More from MiningWrap
The whole sector in one weekly read.
Deals, policy and markets — every Thursday.
Discussion
Loading comments…