Sibanye-Stillwater prices $500m bond to cut debt and push out maturities
An oversubscribed notes sale and linked tender offers targeted a reduction of up to $250m in group borrowings
Sibanye-Stillwater's US subsidiary, Sibanye-Stillwater UK Financing Plc, priced an oversubscribed offering of $500m in senior notes due 2031 carrying a 6.25% coupon, the company confirmed on 8 May 2026. The proceeds were earmarked largely to fund simultaneous tender offers for two older series of notes issued by its Stillwater Mining Company subsidiary: the 4.000% notes due 2026 and the 4.500% notes due 2029.
How the refinancing worked
Of the $675m outstanding on the 2026 notes, holders tendered $613.9m for repurchase, leaving a residual balance to be repaid from cash reserves when that tranche matures. For the 2029 notes, of which $525m was outstanding, holders tendered $175.6m, but Sibanye-Stillwater capped its buy-back of that series at $75m, taking only the capped amount. Combined, the transactions were structured to reduce the group's overall gross debt by up to $250m while replacing near-term, lower-coupon maturities with a single longer-dated instrument.
Why the balance sheet matters now
Sibanye-Stillwater has carried a heavier debt load than most of its South African platinum-group-metals peers since its 2017 acquisition of the US-based Stillwater Mining Company, a deal originally funded through a rights issue and convertible bonds. Higher PGM prices through 2025 and 2026 have improved the group's cash generation and credit profile, giving management room to proactively manage upcoming maturities rather than wait for them to come due. Ratings agencies, including S&P Global Ratings, assigned preliminary ratings to the new notes as part of the process.
Context for South African PGM producers
The refinancing illustrates how improved commodity prices are flowing through to balance-sheet decisions across the platinum sector, not just to dividends. Where Gold Fields and other gold miners have used higher prices to fund larger buybacks, Sibanye-Stillwater's priority has been to de-risk a balance sheet still carrying the legacy of its US platinum and palladium expansion, positioning the group to weather any future downturn in PGM prices from a stronger footing.
Ratings agencies welcomed the transaction as a sign of improving financial discipline, though several noted that Sibanye-Stillwater's overall debt burden, while reduced, remains higher than most of its South African PGM peers, leaving further deleveraging as a priority even as commodity prices stay supportive.
Sources
- Mining Weekly: Sibanye-Stillwater prices oversubscribed $500-million notes offering, 08 May 2026
- Mining Weekly: Sibanye-Stillwater launches cash tender offer for outstanding debt securities, 06 May 2026
- Yahoo Finance / Sibanye-Stillwater: Sibanye Stillwater Limited announces offers to purchase for cash of its 4.000% Senior Notes due 2026 and 4.500% Senior Notes due 2029, 06 May 2026
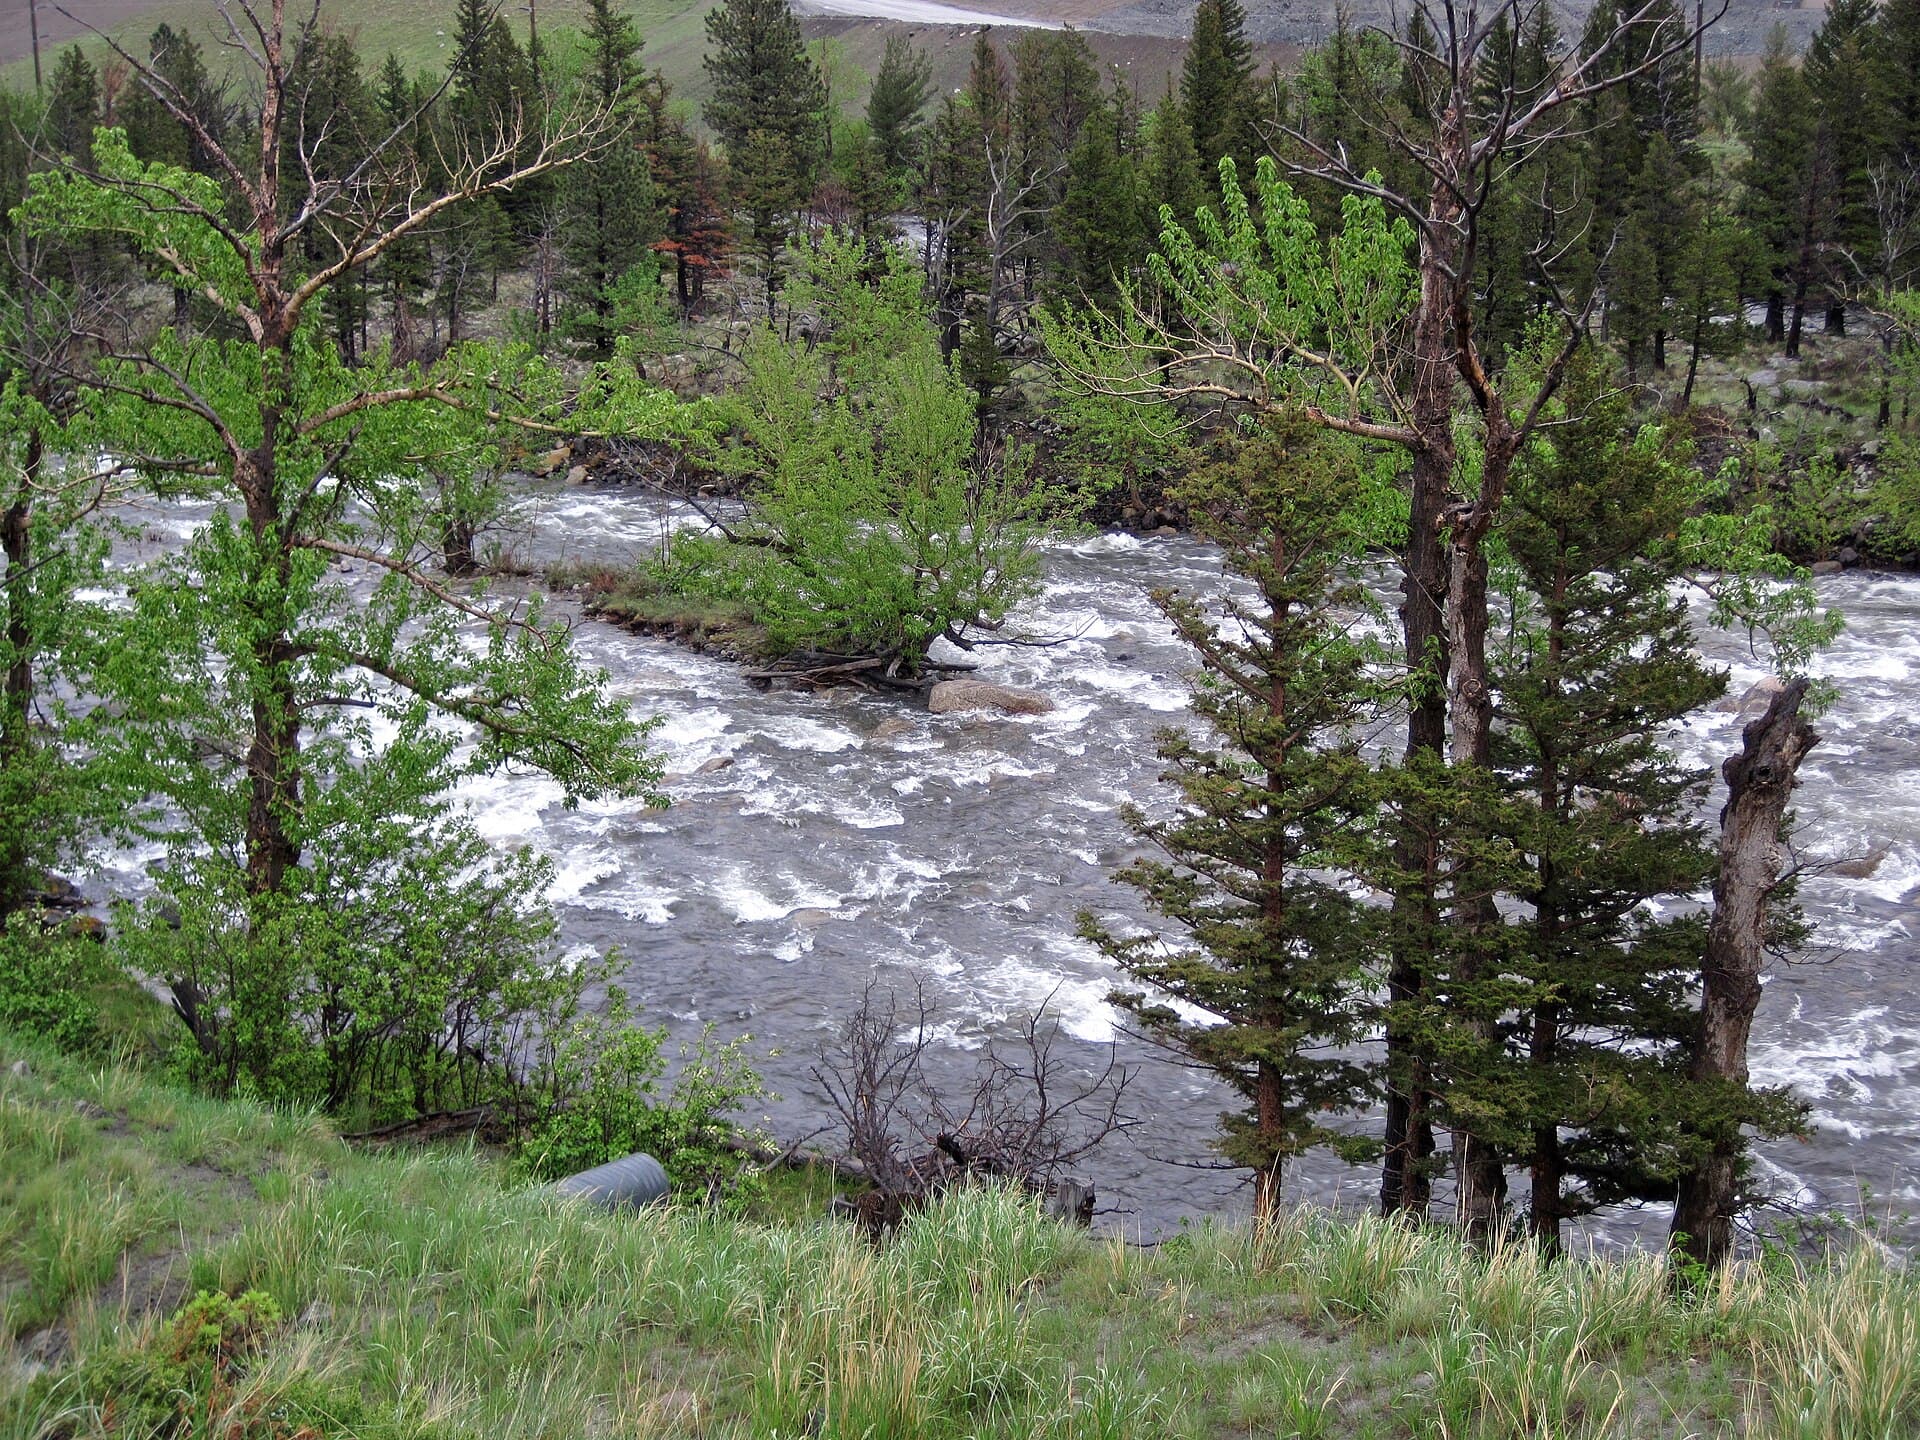
Photo: The area near the Stillwater Mine in Montana, USA, the palladium and platinum operation Sibanye-Stillwater acquired in 2017 and whose debt it has been refinancing. James St. John, Wikimedia Commons, CC BY 2.0.
Was this useful?
More from MiningWrap
The whole sector in one weekly read.
Deals, policy and markets — every Thursday.
Discussion
Loading comments…